Women now own 15.7 million businesses in the United States, 40.6 percent of all companies nationwide, according to Wells Fargo’s 2026 Impact of Women-Owned Businesses report. That ownership share grew 12.1 percent between 2022 and 2025, nearly double the growth rate for men-owned businesses over the same period. Yet on the funding side, companies founded solely by women captured just 1 percent of total U.S. venture capital in 2024, down from 2 percent the year before, according to PitchBook data. Ownership is growing. Access to the capital that lets a business scale is not.
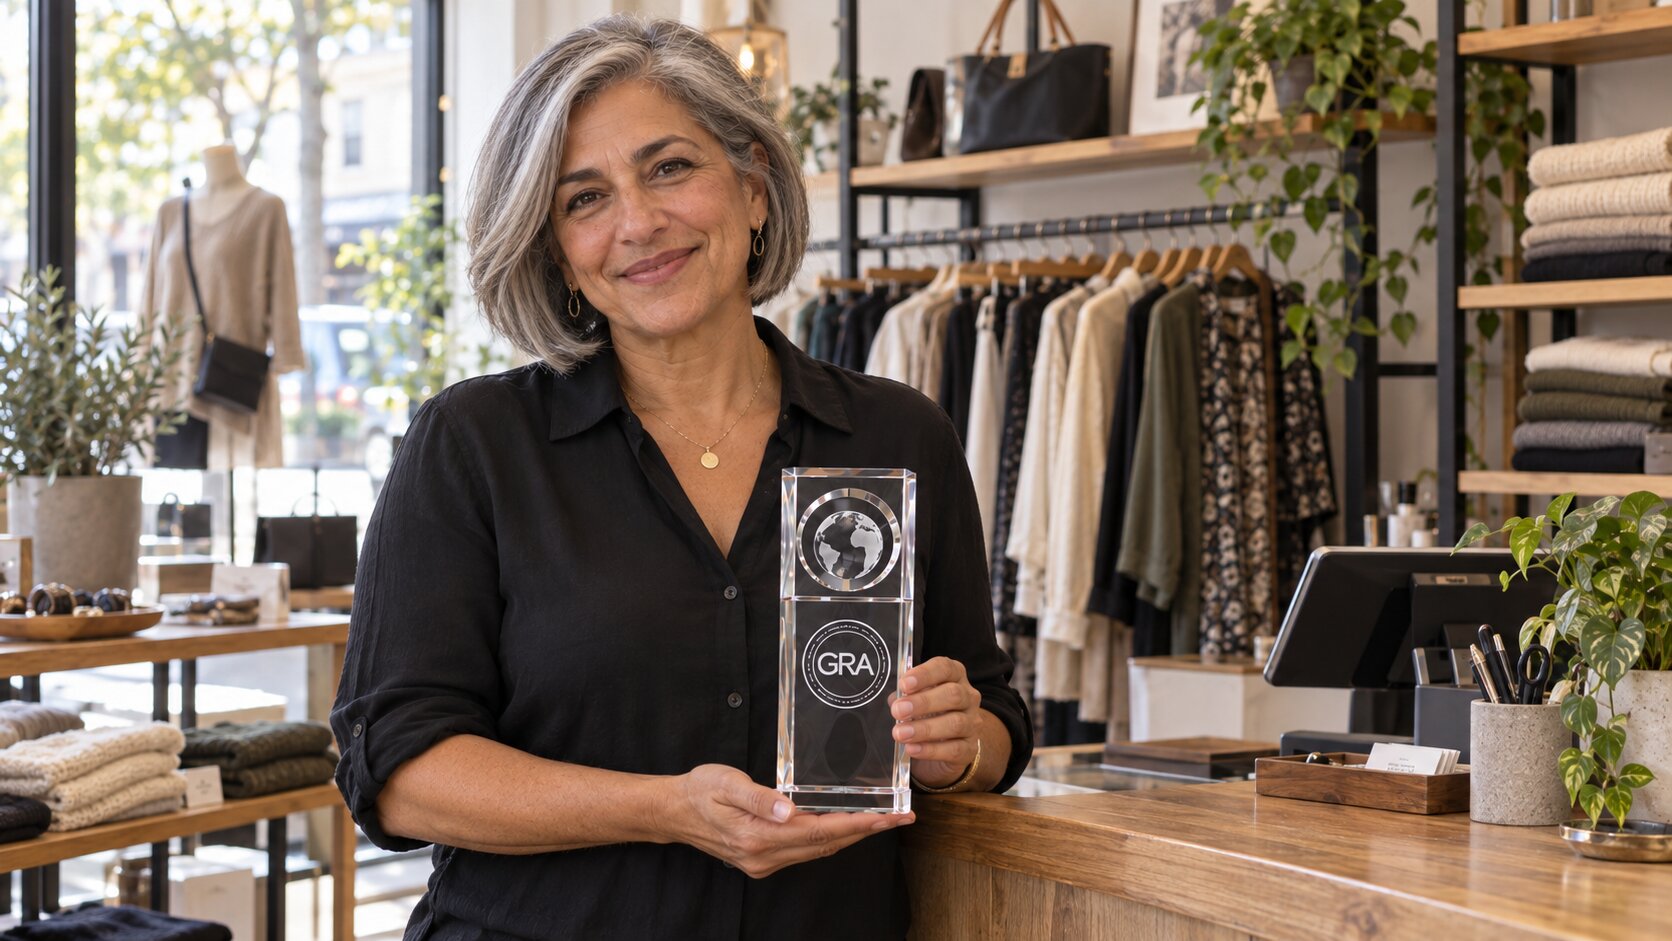
That gap does not close through better pitches alone, since the mechanism behind it runs deeper than any single meeting. It runs through warm introductions, existing networks, and the kind of institutional trust that flows more easily to founders who already look like the last founder a fund backed. Independent recognition offers a different lever entirely. A win from a program like the Global Recognition Awards produces a public, third-party credential that does not depend on already being inside the network that controls the referral.
That distinction matters because the underlying performance case for backing women founders is not the problem. The visibility case is.
The funding gap does not track a performance gap.
Boston Consulting Group research, still cited today for lack of a more recent large-scale replication, found that women-founded companies generated 78 cents in revenue for every dollar of funding invested, compared to 31 cents for male-founded companies over the same period. Women-led startups also report a 60 percent bootstrapped success rate, more than the 35 percent seen among venture-backed peers overall, a pattern several founders attribute to leaner, more disciplined operating habits built out of necessity rather than choice.
None of that has moved the venture capital allocation numbers in any meaningful way. Nearly three-quarters of U.S. venture firms still have no female investing partner at all, and the 30-year historical average for all-female founding teams sits at roughly 2.4 percent of total VC dollars, almost identical to where it stood in 2018. A funding market that keeps producing the same allocation despite stronger unit economics is not pricing in performance. It is pricing in familiarity, and familiarity is exactly the kind of bias an independent, public credential is built to interrupt.
Independent recognition becomes a substitute channel for visibility.
A venture capital introduction is, at its core, a trust transfer: one person vouching for another inside a closed network. Women founders report having less access to that specific mechanism, not less merit to justify it. A published, dated award listing works through a different channel entirely. It does not require an introduction from inside the fund. It sits publicly where any investor, journalist, or customer doing basic diligence can find it on their own, which makes it one of the few credibility signals a founder can generate without first getting access to the rooms the gap keeps her out of.
That is a real, if partial, function. A win becomes a line in a pitch deck an unfamiliar investor can verify independently, a press mention that surfaces when a fund’s associate researches the company before a first call, a credential that travels on its own rather than requiring a warm introduction to carry it.
An award does not replace capital, and should not be sold as if it does
None of this closes a 99-percentage-point funding gap on its own, and treating a recognition program as a solution to a structural capital allocation problem would be its own kind of overselling. The Global Recognition Awards charges an entry fee like most credentialing programs of its kind, a cost that itself falls harder on founders with less access to capital in the first place, which is worth naming honestly rather than glossing over. The program has also not published demographic data about its own winners, so its role in closing this specific gap is inference, not something the program itself has measured or claimed.
What a credential can do is add one verifiable data point to a fundraising case that still has to succeed on its own terms, in a market where the data says performance already speaks for itself and is still not being heard.
The gap will not close through visibility alone, but visibility is the piece founders can build without waiting for the capital markets to move first. A public credential, a press feature, a verifiable track record assembled in public rather than kept in a private deck: these are the tools available right now to a founder locked out of the referral networks that still decide who gets funded and on what terms. The 78-cent return the data already shows will not sell itself. It has to be seen by someone with a checkbook who was never going to take the meeting otherwise.